Feather Robotics Launches Modular Platform to Capture Developer Ecosystem
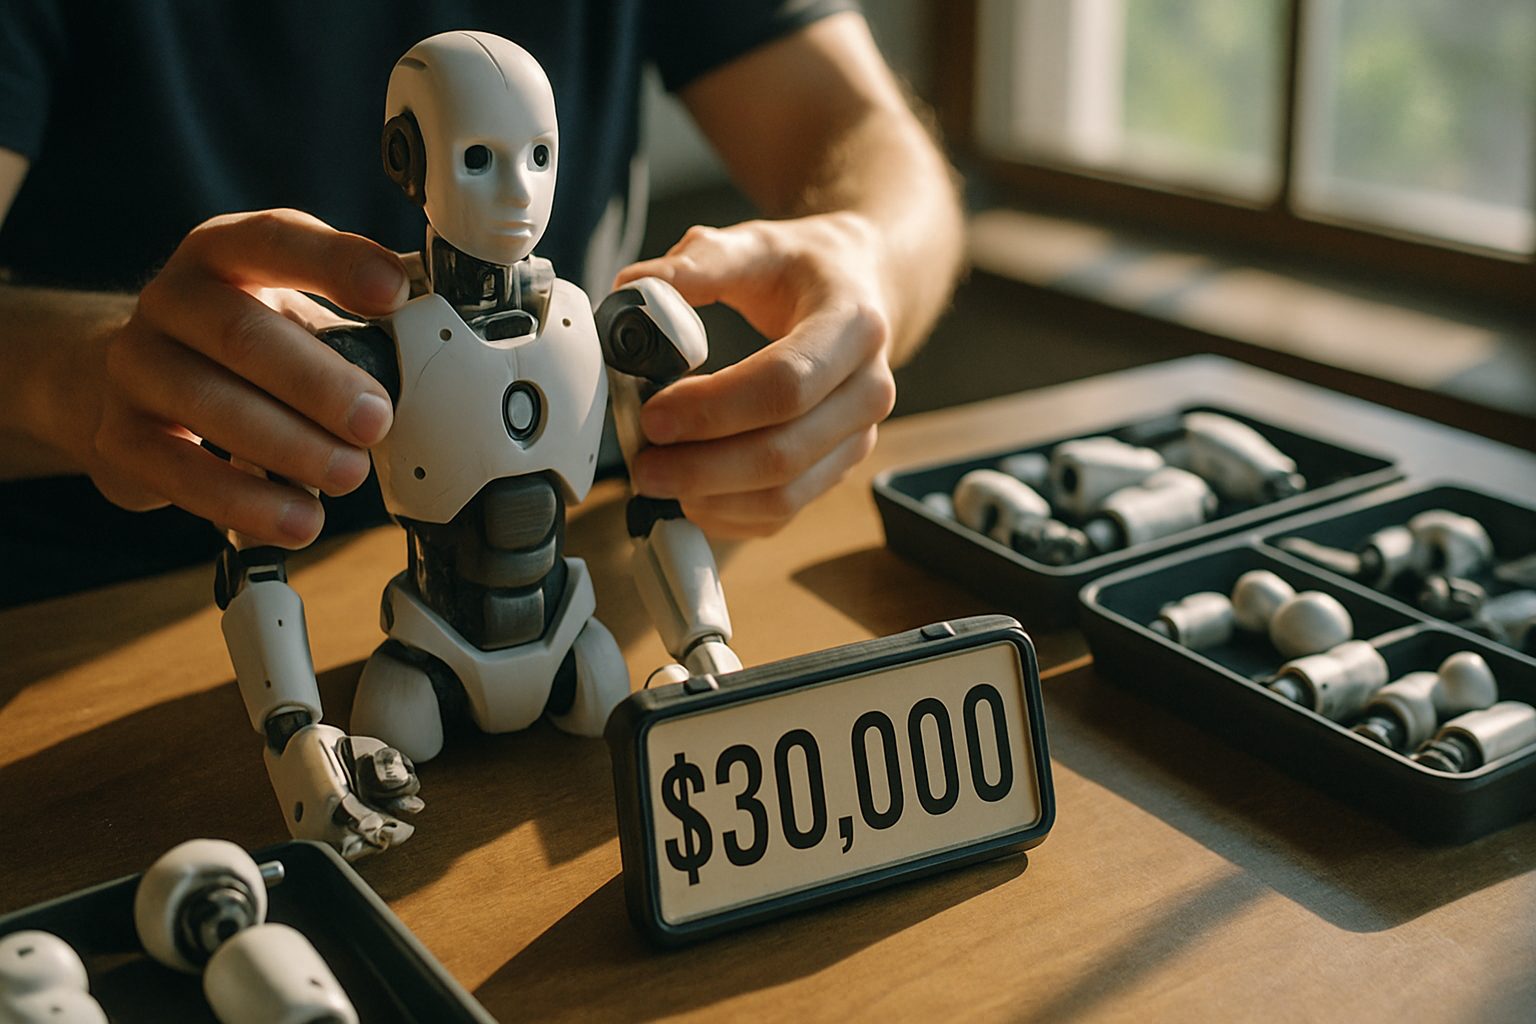
TL;DR: Feather Robotics is positioning itself as the “Android of robotics” by offering a $30,000 modular humanoid platform for developers, undercutting competitors while capturing an emerging market for deployable robotic systems. The startup has already surpassed $1M in revenue post-$7.6M pre-seed funding.
The Business Case: Practical Robotics Over Moonshots
Feather’s fundamental advantage lies in operational readiness. While Tesla and Figure pursue general-purpose humanoids with unreleased foundational models, Feather sells working robots today. This positions the startup to capture developers and integrators building real-world solutions now, rather than betting on distant breakthroughs.
At $30,000 per unit—roughly half the price of comparable Chinese alternatives like Unitree’s H2 Edu—Feather hits an attractive price point for labor replacement. The economics are stark: hiring a human laborer costs $50,000-$60,000 annually plus onboarding overhead. A Feather robot becomes cost-competitive while remaining flexible across tasks.
Market Position: Closing a Strategic Gap
According to TechCrunch’s reporting, Gradient Ventures partner Darian Shirazi identifies Feather as the only U.S. startup developing a modular humanoid platform at scale. The company occupies a distinct middle tier: above domestic robot builders like Sunday, below generalist plays from Figure and Tesla.
Foreign trade restrictions on Chinese robotics hardware have inadvertently strengthened Feather’s moat. Domestic procurement requirements will funnel enterprise customers toward the available American alternative, at least until competitors emerge.
Technical Architecture: Ecosystem-First Design
Feather’s modularity is its core differentiator. Customers can adjust arm lengths and other hardware specifications for specific use cases—restaurants, labs, logistics environments. This customization reduces the need for one-size-fits-all engineering.
The platform’s software layer supports any leading robotics AI provider: Nvidia, Skild, or Physical Intelligence. This agnostic approach mimics Android’s success by letting developers and AI vendors compete on intelligence layers rather than forcing proprietary stacks. Early deployments show robots functioning as kitchen workers and lab cleaners.
Execution and Burn Rate
Feather has raised only $7.6M pre-seed but has spent “a fraction” of that capital while generating over $1M in revenue, according to Shirazi. This capital efficiency suggests strong unit economics and limited infrastructure bloat—a marked contrast to robotics startups burning $10M+ annually on R&D with no revenue.
Founder Hoa Mai notes the startup has completed extensive field testing and resolved manufacturing issues over the past year. A “big product launch” is imminent, implying production scaling is the next lever.
Background: The Founders and Market Context
Hoa Mai previously founded a humanoid startup acquired by 1X in 2025, giving him domain expertise in platform design and manufacturing. Parsa Bakhtiari, co-founder, engineered the Tesla Model 3 and reported directly to Elon Musk, bringing automotive supply-chain and manufacturing discipline to a historically capital-inefficient sector.
Feather Robotics launched in 2025 with backing from Gradient Ventures, Google’s venture arm. The $7.6M pre-seed round was led by Gradient in a previously announced funding event.
Gradient Ventures invests in deep tech and AI companies, typically taking a 5-10 year horizon. Its conviction in Feather signals confidence in the modular platform thesis over speculative general-purpose robotics.
The robotics market currently lacks consensus on timing for general-purpose humanoids. Industry leaders disagree whether the “ChatGPT moment” arrives in years or a decade. Feather’s bet: developers and enterprises will capture real value from specialized, deployable systems in the interim—and the ecosystem leader in that transition wins long-term.
Chinese competitors like Unitree have built modular platforms at lower absolute costs ($60K+ for H2 Edu), but U.S. import restrictions and domestic procurement preferences create a moat Feather can exploit while competitors establish supply chains.
Investment Implications
Feather exemplifies a pattern that reshapes venture outcomes: pragmatic platforms beat utopian moonshots. By enabling a developer ecosystem around imperfect but deployable hardware, Feather creates switching costs and network effects that general-purpose robots cannot yet offer.
The $1M+ revenue run-rate suggests early product-market fit. If Feather maintains capital efficiency while scaling production, Series A will likely be oversubscribed and priced aggressively upward—a rare position in hardware.
Downside risks remain: manufacturing complexity, AI model integration delays, and competition from better-capitalized players entering the space. But Feather’s window to establish developer mindshare and install base is now, before Tesla or Figure’s systems reach deployment. Early execution matters more than theoretical capability.
About the Author